Does Medicare Cover Home Oxygen?
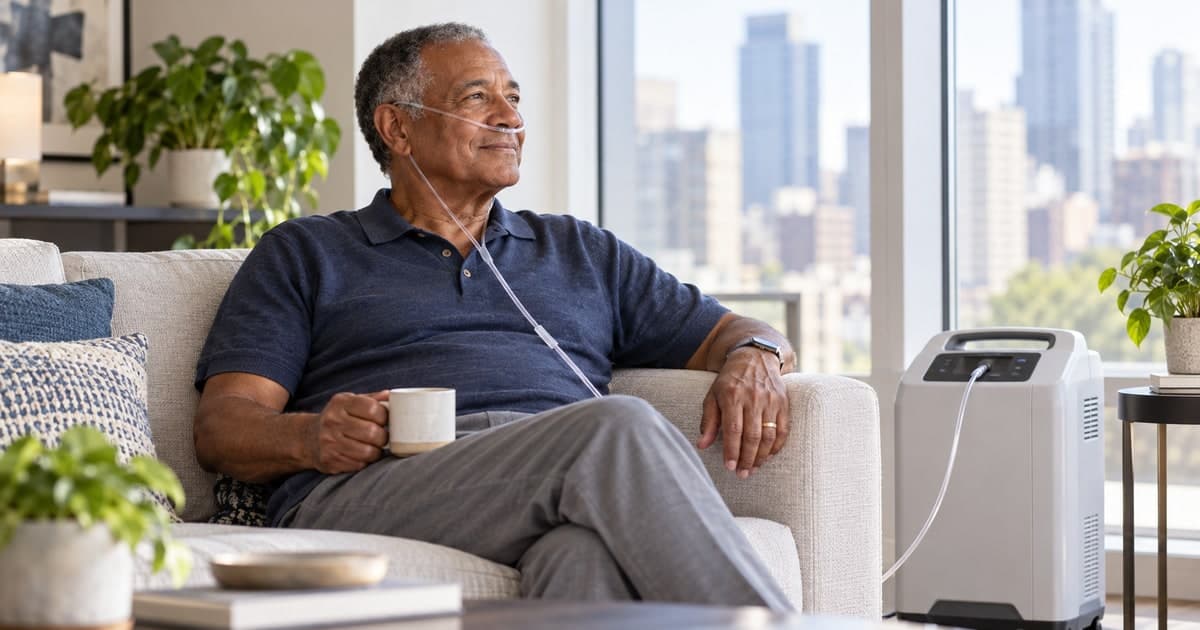
Medicare Part B can cover oxygen and oxygen equipment used at home when your condition, test results, provider order, and supplier meet Medicare requirements.
Clear perspectives on health, care, and coverage. Helping you find your way through it all.
Medicare Part B can cover oxygen and oxygen equipment used at home when your condition, test results, provider order, and supplier meet Medicare requirements.
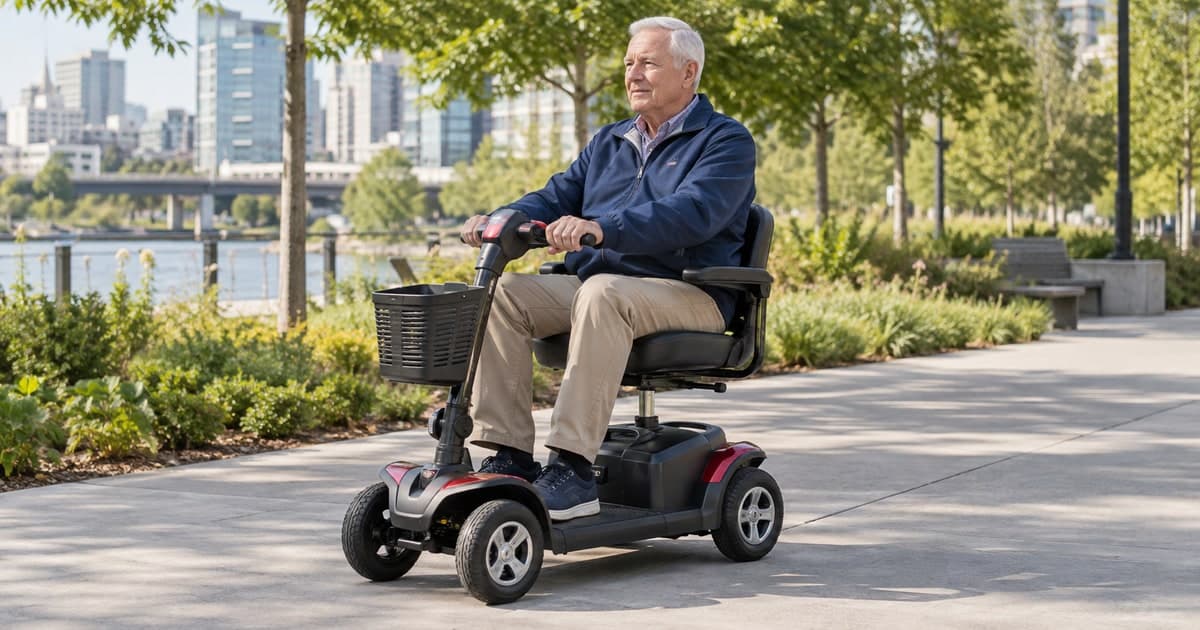
Medicare Part B can cover a medically necessary wheelchair or power scooter for use in your home when evaluation, prescription, supplier, and documentation rules are met.
Medicare Part B may cover a CPAP machine and supplies for obstructive sleep apnea, beginning with a 12-week trial when eligibility requirements are met.
Medicare Part B may cover cataract surgery that removes the cloudy lens and implants a conventional intraocular lens when coverage requirements are met.
Original Medicare generally does not cover a routine annual physical. Part B instead covers a one-time Welcome to Medicare visit and yearly Wellness visits.
The Welcome visit is a one-time preventive appointment during your first 12 months of Part B. A yearly Wellness visit has separate timing rules, including spacing after a Welcome visit.
Start with Medicare Care Compare or your plan's directory, then call the office to confirm coverage, location, assignment or network status, and new-patient availability.
Contact your plan as soon as you learn a doctor is leaving. Confirm the effective date, ask about continuity protections, and identify an in-network replacement before your next visit.
Original Medicare usually does not require a referral to see a specialist. Medicare Advantage rules depend on the plan, and HMOs commonly require referrals.
A doctor who accepts Medicare assignment cannot charge more than the Medicare-approved amount for a covered service. Some non-participating doctors may charge a limited additional amount.
An Advance Beneficiary Notice of Noncoverage, or ABN, is a written warning that Original Medicare may not pay for a proposed item or service.
The Medicare-approved amount is the payment amount Original Medicare sets for a covered service or item. It is the basis for calculating Medicare's share and yours.
Original Medicare has no yearly out-of-pocket maximum for Part A and Part B. Medicare Advantage plans do have an annual limit for covered medical services.
IRMAA is an extra amount some higher-income beneficiaries pay for Medicare Part B and Part D. Social Security usually bases it on tax information from two years earlier.
No. A $0 premium means the plan charges no additional monthly plan premium. You generally still pay the Part B premium and the plan's other out-of-pocket costs.
Plan G generally provides more complete Part B cost protection. Plan N can have a lower premium but uses certain copayments and does not cover Part B excess charges.
A Dual Eligible Special Needs Plan, or D-SNP, is a Medicare Advantage plan for people who have both Medicare and Medicaid.
A Special Needs Plan is a type of Medicare Advantage plan that tailors benefits, provider choices, drug coverage, and care coordination to a defined group.
HMOs generally use stricter provider networks and often require specialist referrals. PPOs usually offer more out-of-network flexibility but may charge more for it.
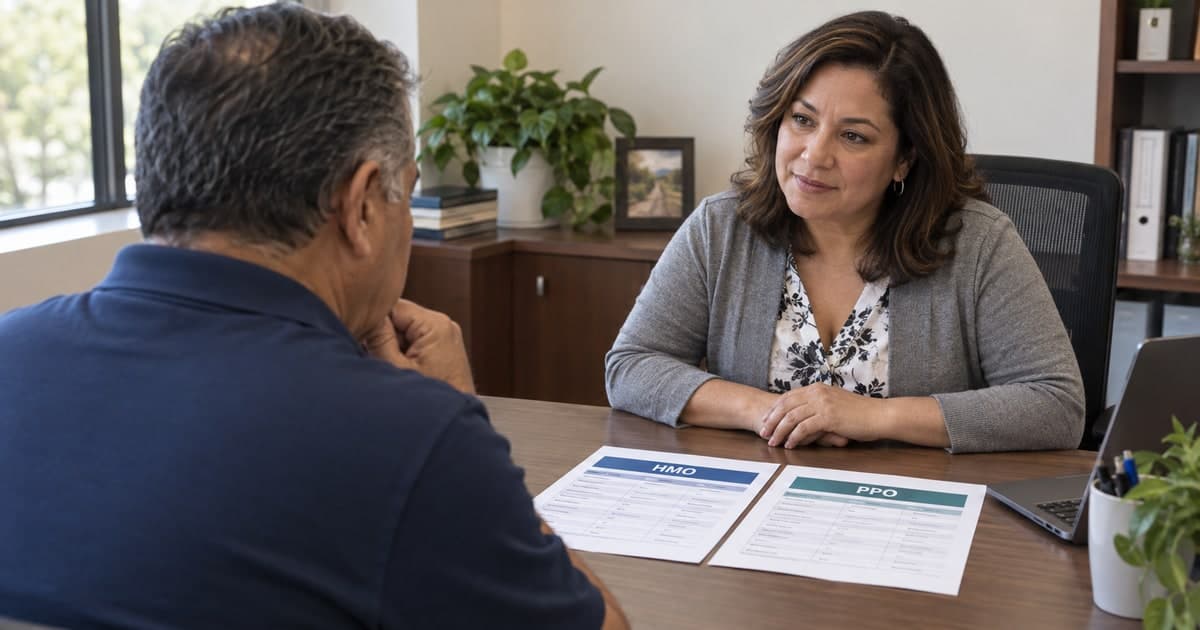
You can join Medicare Advantage during specific enrollment periods if you have Part A and Part B and live in the plan's service area.
You can leave Medicare Advantage during certain enrollment periods. Before switching, coordinate prescription drug coverage and determine whether you can buy Medigap.
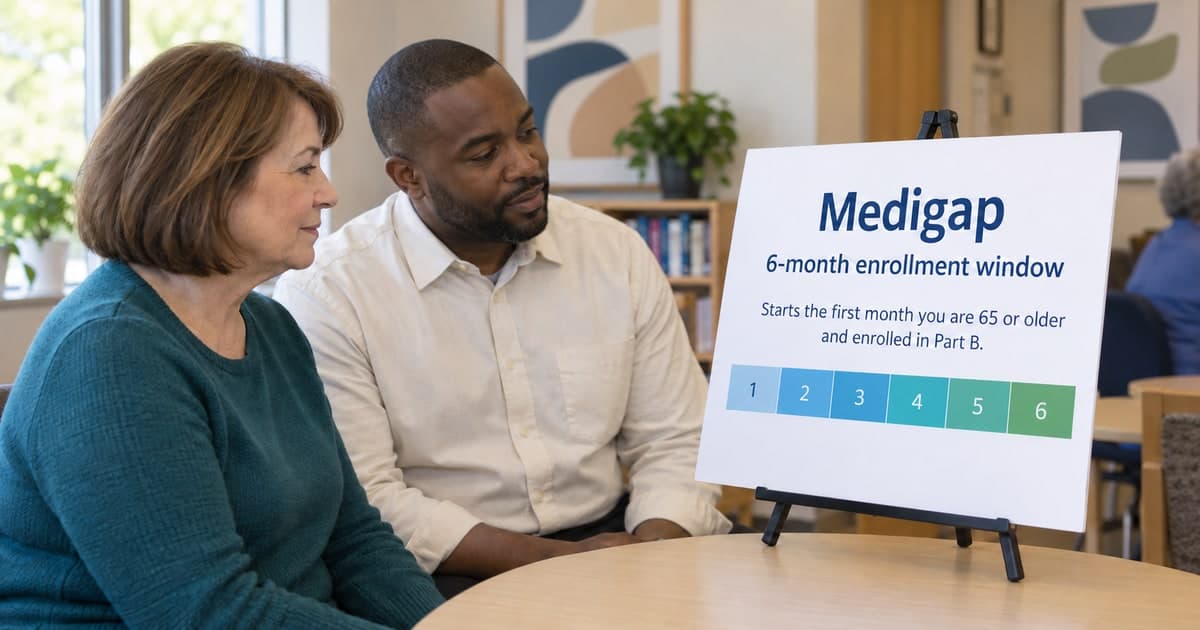
Your federal Medigap Open Enrollment Period lasts six months. It starts the first month you are 65 or older and enrolled in Medicare Part B.
Medicare Advantage Open Enrollment runs from January 1 through March 31. If you are already in Medicare Advantage, you can make one plan change during this period.
The Medicare General Enrollment Period runs from January 1 through March 31 each year. It is a chance to enroll in Part B or premium Part A after missing another enrollment period.
You can often delay Part B without a late penalty while covered by a group health plan based on your or your spouse's current employment. Not every type of insurance qualifies.
Most people need both Part A and Part B for broad hospital and medical coverage. You also need both parts to join a Medicare Advantage plan.
Part A is mainly hospital insurance. Part B is medical insurance for doctors, outpatient care, equipment, preventive services, and other medically necessary care.
Medicare Part C is another name for Medicare Advantage. It lets you receive your Part A and Part B benefits through a Medicare-approved private health plan.
Medicare Part B is medical insurance. It helps cover medically necessary doctor and outpatient services, preventive care, durable medical equipment, and several other types of care.
Medicare Part A is hospital insurance. It helps cover eligible inpatient hospital care, short-term skilled nursing facility care, hospice, and certain home health services.
A caregiver can help organize coverage, compare plans, track claims, and prepare for appointments. Before Medicare shares private information, the beneficiary must authorize that access.
Original Medicare generally continues anywhere in the United States with participating providers. Medicare Advantage and Part D plans use service areas, so a move may create a Special Enrollment Period.
People with Medicare and Medicaid may have full Medicaid benefits or more limited help with Medicare costs. The category of assistance determines which benefits and billing protections apply.
When you have Medicare and employer insurance, one plan pays first and the other pays second. Current employment, employer size, disability status, and retiree or COBRA coverage determine the order.
You may be able to delay Medicare Part B without a penalty if you have group health coverage through your or your spouse's current employment. The employer's size and type of coverage matter.
Creditable prescription drug coverage is expected to pay, on average, at least as much as standard Medicare Part D. It can let you delay Part D without a late-enrollment penalty.
Part D plans contract with pharmacy networks. Preferred in-network pharmacies often cost less than standard pharmacies, while out-of-network prescriptions may not be covered except in limited situations.
Extra Help is a Medicare program that lowers Part D premiums, deductibles, and prescription costs for people with limited income and resources.
In 2026, your out-of-pocket spending for covered Part D drugs is capped at $2,100. After reaching the limit, you pay no copayment or coinsurance for covered Part D prescriptions for the rest of the year.
Step therapy requires you to try a plan-preferred medication before the plan covers another drug. Your prescriber can request an exception when the required drug may be ineffective or harmful.
Prior authorization means your Part D plan requires information showing that a prescription meets its coverage rules before the plan will pay for it.
A formulary is a Medicare drug plan's list of covered prescriptions. It also shows drug tiers and rules such as prior authorization, step therapy, and quantity limits.
Compare Part D plans using your exact medications, dosages, and pharmacies. A low premium can cost more overall if your drugs are excluded, placed on expensive tiers, or restricted.
Medicare covers a range of diabetes services and supplies, including screenings, glucose monitors, insulin, self-management training, certain foot and eye care, and prevention programs.
Medicare Part B covers certain vaccines, including flu, COVID-19, pneumococcal, and qualifying hepatitis B shots. Part D covers other recommended adult vaccines such as shingles, RSV, and Tdap.
Medicare Part B covers many telehealth services. Under current rules, Medicare covers qualifying telehealth received anywhere in the United States, including at home, through December 31, 2027.
Medicare Part B covers acupuncture only for qualifying chronic low back pain. It covers up to 12 treatments in 90 days, with eight additional treatments if you improve.
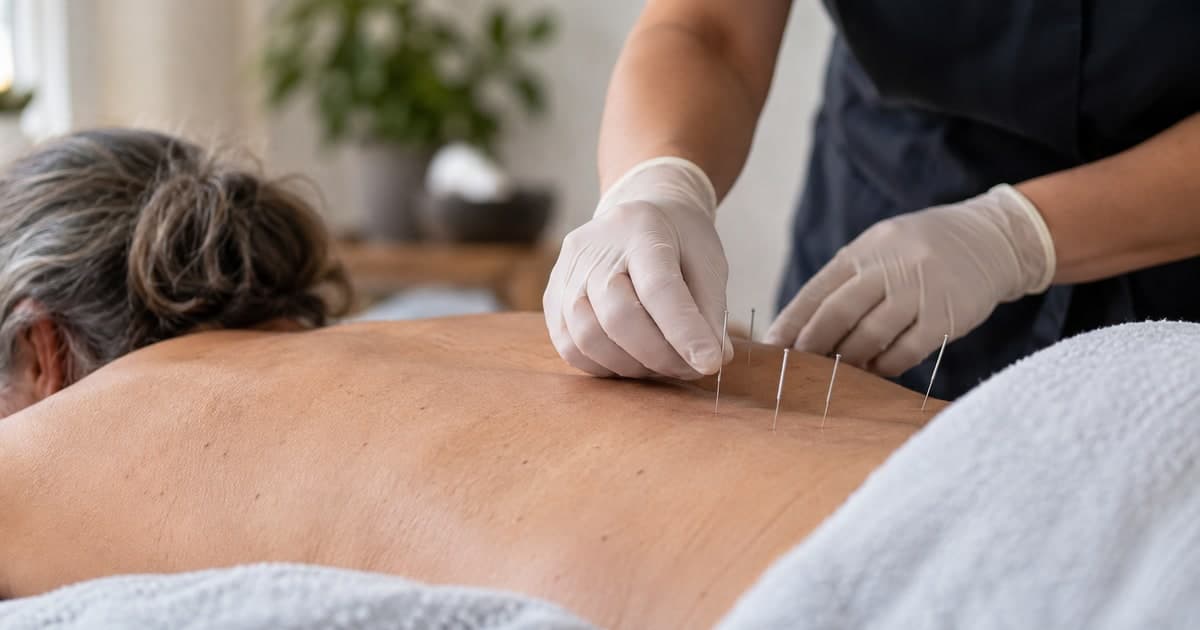
Medicare Part B covers manual manipulation of the spine by a chiropractor to correct a qualifying subluxation. It does not generally cover other services or tests performed or ordered by the chiropractor.
Medicare Part A covers hospice for eligible people with a terminal illness who choose comfort-focused care instead of treatment intended to cure that illness.
Medicare generally does not cover long-term custodial care in a nursing home, assisted living facility, or private home. It may cover short-term skilled nursing or rehabilitation when strict requirements are met.