
Your federal Medigap Open Enrollment Period lasts six months. It starts the first month you are 65 or older and enrolled in Medicare Part B.
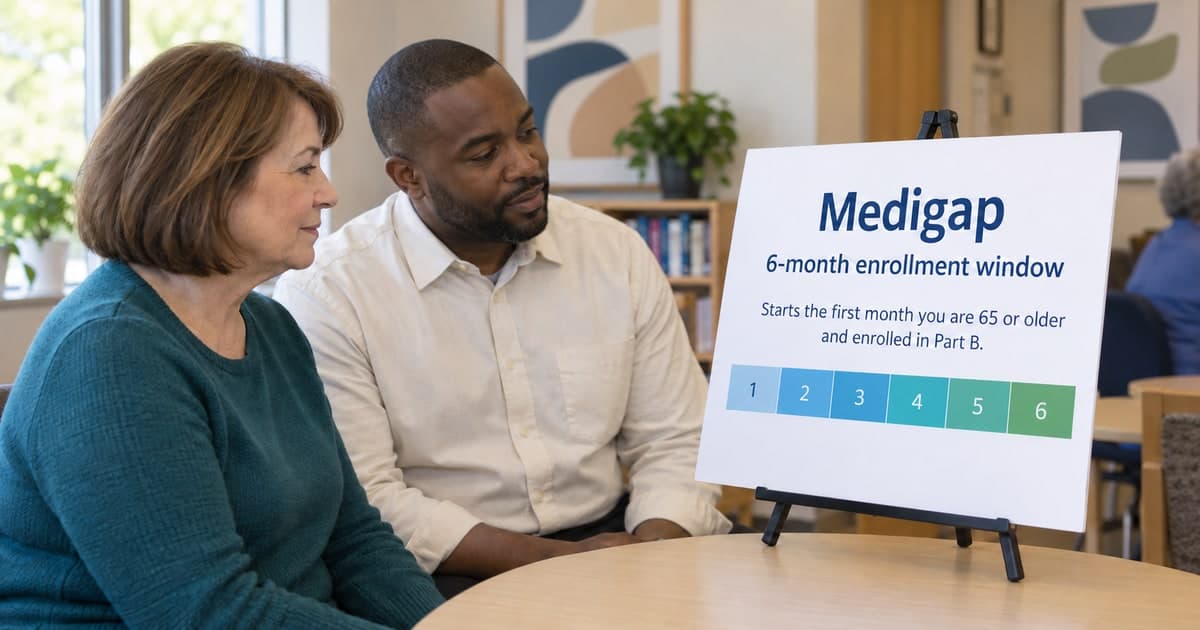
Medigap helps pay some of the deductibles, copayments, and coinsurance left by Original Medicare. When you apply matters. Outside a protected enrollment period, an insurer may review your health history before deciding whether to sell you a policy or what to charge. This is called medical underwriting.
What Protection Do You Get?
During your six-month Medigap Open Enrollment Period, you can buy any Medigap policy available to people in your situation in your state. An insurer cannot deny the application or charge more because of a health problem.
This window begins with Part B at age 65 or older. If you delay Part B because of current-employment coverage, your window generally begins when that delayed Part B coverage starts.
Example: if you are 65 or older and Part B begins June 1, the six-month window runs June through November. If you apply in December, the insurer may review your health history unless another protection applies. If Medicare began before 65, a new federal Medigap open-enrollment window arises when you turn 65; protections before 65 vary by state.
Does It Return Every Year?
No. Medigap Open Enrollment is not the October 15–December 7 Medicare Open Enrollment Period. It generally happens once.
After it ends, an insurer may be allowed to review your health, charge more, or decline an application unless you have a federal guaranteed-issue right, which requires insurers to offer certain policies, or stronger protection under state law.
During open enrollment, the insurer cannot deny you a policy or charge more because of your health. In some cases, you may still have to wait before it pays for conditions you already have. Previous insurance that counts as creditable coverage can shorten or remove that wait. Ask the insurer for the start date and any waiting period in writing. Medicare’s Medigap guide explains the distinction.
What Should You Compare?
Compare the same plan letter and version across insurers. Massachusetts, Minnesota, and Wisconsin standardize policies differently. Standardized plans with the same letter provide the same basic medical benefits, but premiums, the way insurers set prices, household discounts, customer service, and future rate increases can differ.
You must have Original Medicare to use Medigap. A Medigap policy does not work with Medicare Advantage.
Calculate the window from the first month you have Part B and are 65 or older, then request quotes for the same standardized benefit from several insurers. If you are under 65 or outside that window, your State Health Insurance Assistance Program (SHIP) can help identify your state’s protections.
Medicare policy sources last checked: October 8, 2026.